
IUL vs Whole Life Insurance: Which Is Better for You?
Choose whole life when contractual cash values and a defined premium schedule are your priorities, including limited-pay options where available. Consider IUL when adjustable funding and index-linked growth potential fit your goals and you accept ongoing review. Compare actual designs: blended whole life and conditional IUL guarantees can change the decision.
Start your IUL vs whole life comparison with the purpose: legacy, family protection or supplemental retirement resources. Both provide permanent coverage but balance certainty and accumulation differently.
Key Considerations
- Separate a guaranteed death benefit from guaranteed cash values and illustrated growth.
- Whole life can include limited-pay schedules and blended term/paid-up-addition designs.
- Compare usable surrender and loan values at the time you expect to need them.
Choose According to Your Main Priority
Favor whole life for contractual values and scheduled payments; consider IUL for adjustable funding and index-linked potential with ongoing review.
Separate lifelong legacy needs from temporary income replacement. Entirely temporary obligations may favor term insurance.
Set coverage, duration and budget first. Our California life insurance guidance explains these priorities. The table compares designs, not guaranteed winners.
Separate Coverage Guarantees From Growth Potential
Whole life can guarantee death benefits and scheduled cash values when contractual premiums and conditions are satisfied. Participating dividends may buy paid-up additions or serve other permitted purposes. In Understanding the Dividend Difference, MassMutual reports paying dividends to eligible participating policyowners every year since 1869. Dividends and dividend-dependent values remain nonguaranteed; that history does not guarantee future payments.
IUL uses index-linked formulas, not stock ownership. Caps limit upside, participation rates determine credited participation, and spreads may reduce credits. Terms may change within contract limits.
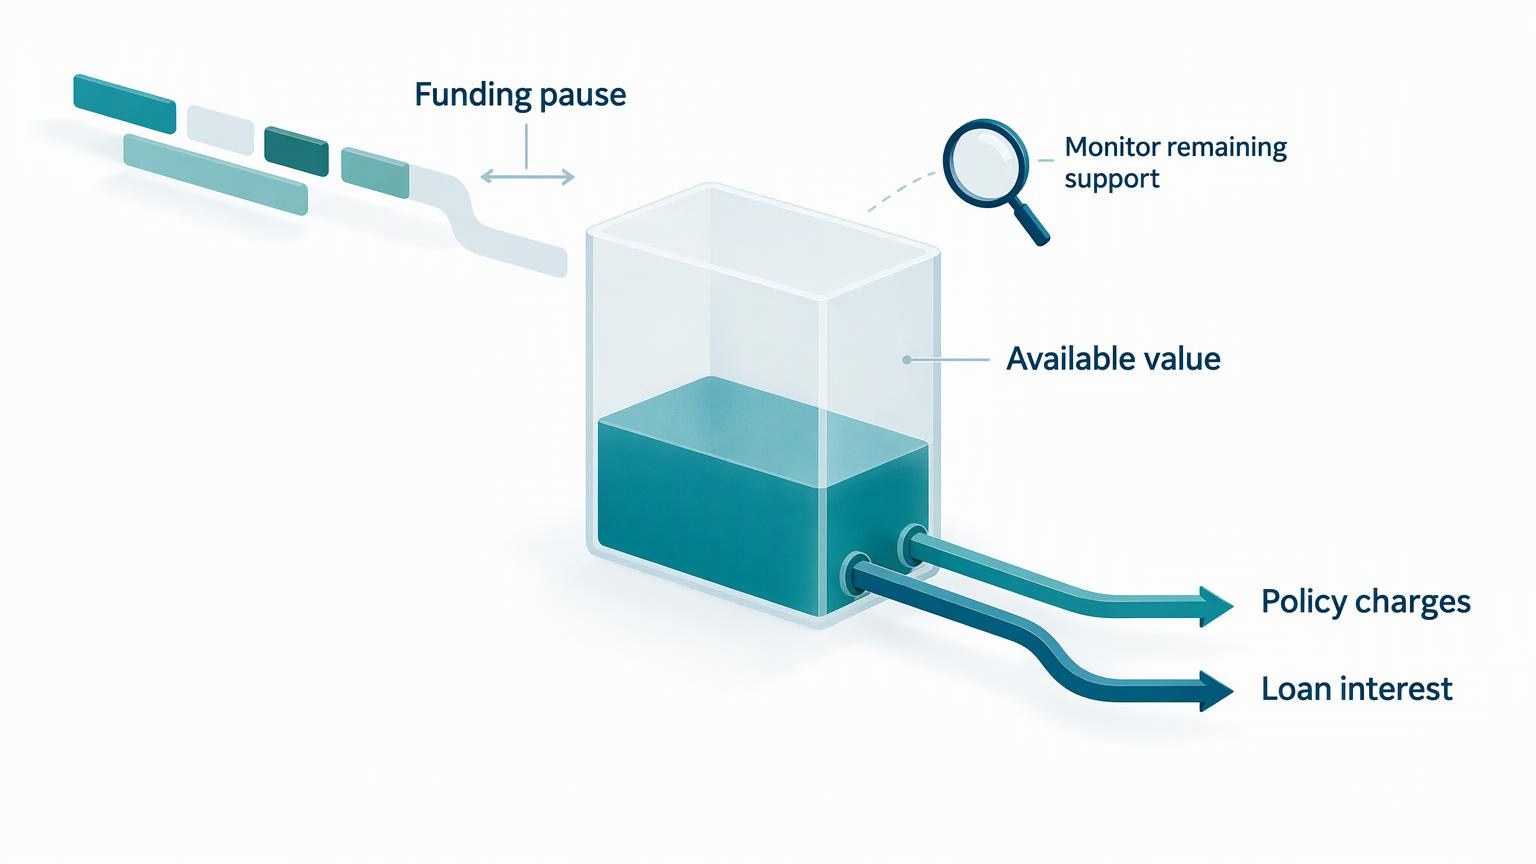
Compare current IUL charges with contractual guaranteed maximum schedules. Current charges determine deductions; maximum schedules establish ceilings, not unchanged future rates. Cost-of-insurance deductions can change with age. Neither schedule is a no-lapse funding test.
Secondary or no-lapse guarantees can preserve coverage despite insufficient account value. Compare duration and funding requirements: protection is not automatically lifelong and guarantees coverage, not spendable cash.
Nationwide's IUL Protector II guide describes an optional extended no-lapse rider and continuing monthly deductions. A crediting floor does not stop charges from reducing value. Guarantees depend on contract conditions and the issuing insurer's claims-paying ability.
| Your Priority | Starting Option | Reason | Trade-Off |
|---|---|---|---|
| Defined values and payments | Scheduled-premium whole life | Contractual values support certainty | Required base premiums follow the schedule |
| A contractual premium deadline | Limited-pay whole life | Base premium duration is defined | Compressed funding must fit your budget |
| Legacy plus temporary protection | Whole life with term/PUA riders, or separate policies | Term adds temporary protection; PUAs add permanent coverage and value | Base, term and optional funding obligations differ |
| Adjustable funding and index-linked potential | IUL | Payment choices accommodate changing priorities | Coverage tests and values require review |
| Temporary protection only | Term insurance | Matches a defined obligation | No cash value |
Compare Funding Designs, Not Flexibility Labels
Whole life offers limited-pay and blended designs; IUL permits adjustable funding within coverage requirements. Separate required payments from optional contributions.
MassMutual's published Whole Life 10 Pay illustration describes ten-year base premiums, with rider durations governed separately. This design example is not a current offer or prediction. Contractually paid-up coverage differs from using dividends to offset premiums.
A single-policy blend can combine a term rider supplying temporary coverage with paid-up-addition (PUA) riders buying permanent insurance and cash value. Separate whole-life and term policies remain alternatives. MassMutual's rider explanation describes these mechanisms and payment limits.
Permitted optional PUA funding, dividend elections and approved coverage adjustments offer choices, but required base premiums remain due. Rider limits and approval govern changes and their effects.
For IUL, planned premiums support your funding goal; they are not contractual no-lapse tests, actual charges or MEC limits. Subtracting a no-lapse premium from your payment does not calculate cash value.
Compare the Funding Schedule You Actually Want
Discuss limited-pay, blended whole-life and IUL designs with Rene Farias based on your coverage goal and sustainable budget.
Compare Cash Access at Your Intended Date
Compare surrender values and available loans at your intended access date. Neither category establishes early liquidity. IUL account value can exceed surrender value because of charges and debt; whole-life access depends on values, additions and loan terms.
Withdrawals remove value; loans incur interest and generally reduce net death proceeds; surrender ends coverage. Lapse or surrender with debt can create taxable gain without a new payment.
Qualifying non-MEC withdrawals generally recover basis first; loans generally are not taxable when taken while coverage remains in force. Exceeding statutory funding tests can create MEC status. MEC distributions, including loans, generally tax gain first, with a potential 10% additional tax before age 59½, subject to exceptions.
MassMutual's illustration explains MEC testing; Nationwide's guide explains access conditions. Our TFRA strategy disclosures add supplemental-income context.
A Hypothetical Choice: Stop Premiums Before Retirement
Suppose a California business owner wants lifelong legacy protection, larger working-years coverage and required base premiums ending before retirement. The owner can sustain scheduled funding and keeps emergency savings separate.
Limited-pay whole life addresses the firm premium deadline. A blend could add temporary term-rider coverage and permanent paid-up additions, with rider obligations distinguished from the paid-up base benefit.
If a weaker business year makes variable funding more important, reduced planned IUL payments may work only while applicable coverage tests remain satisfied and account value or valid no-lapse protection supports coverage. Review that scenario first: reduced funding can lower future values and require catch-up payments. Whole life may also permit reduced optional PUA funding while base premiums continue.
Compare limited-pay first for a contractual deadline, IUL for variable funding. Illustrated premium cessation is not contractual paid-up status.
Work With Rene Farias to Compare Actual Proposals
Match coverage, insured person and funding horizon. Lower premiums may reflect less permanent protection or more nonguaranteed assumptions.
- Set coverage and sustainable funding.
- Compare guaranteed values with conservative dividend or crediting assumptions.
- Review rider payments, surrender values, loan costs and reduced-funding effects.
Reconcile the issued contract and illustration before acceptance; underwriting determines the offer.
Rene Farias is an independent insurance advisor based in Los Angeles, serving California clients across multiple carriers. Zoom strategy sessions help compare insurance options. Tax and legal implementation requires appropriate advisers.
Work With Rene Farias
Rene Farias works with California families, professionals and business owners to compare insurance-based protection and retirement-planning strategies. He is based in Los Angeles and offers strategy sessions over Zoom.
Frequently Asked Questions
Should I Replace an Existing Policy to Get a Better Illustration?
Not on illustrations alone. Your existing policy may have guarantees, accumulated values or provisions a replacement cannot preserve. Compare surrender costs, outstanding debt, new underwriting and replacement funding requirements. Weigh what you relinquish against the new design's potential benefits first.
Can I Own Both IUL and Whole Life?
Yes. Separate policies can address contractual legacy protection and supplemental accumulation potential. Both must fit your combined coverage needs and sustainable budget. Compare the arrangement with one appropriately designed policy; additional contracts do not necessarily create a better overall plan.
Do Beneficiaries Receive Cash Value Plus the Death Benefit?
Not automatically. Payment depends on the death-benefit structure, additions, riders and outstanding debt. Cash value is not necessarily a separate inheritance. Compare actual net death proceeds at relevant ages, rather than adding cash-value and death-benefit columns, to understand beneficiaries' protection.
Is a TFRA or LIRP a Different Insurance Product?
No. TFRA and LIRP are strategy labels, not separate IRS account types. IUL or whole life may support supplemental protection and cash-value planning. Benefits depend on funding design and permitted access; non-MEC status and continued maintenance matter for tax treatment.
Does Either Policy Automatically Include Long-Term Care Coverage?
No. Riders vary by contract and state; accelerated death benefits are not automatically comprehensive long-term care insurance. Dedicated linked-benefit care coverage can complement separate legacy insurance. Compare eligibility triggers, care benefits and reductions to the linked policy's own remaining death benefit.
Choose Your Coverage and Funding Priorities
Prepare your desired benefit, premium-end date and existing policy information for a Zoom strategy session with Rene Farias to compare designs against your goals.